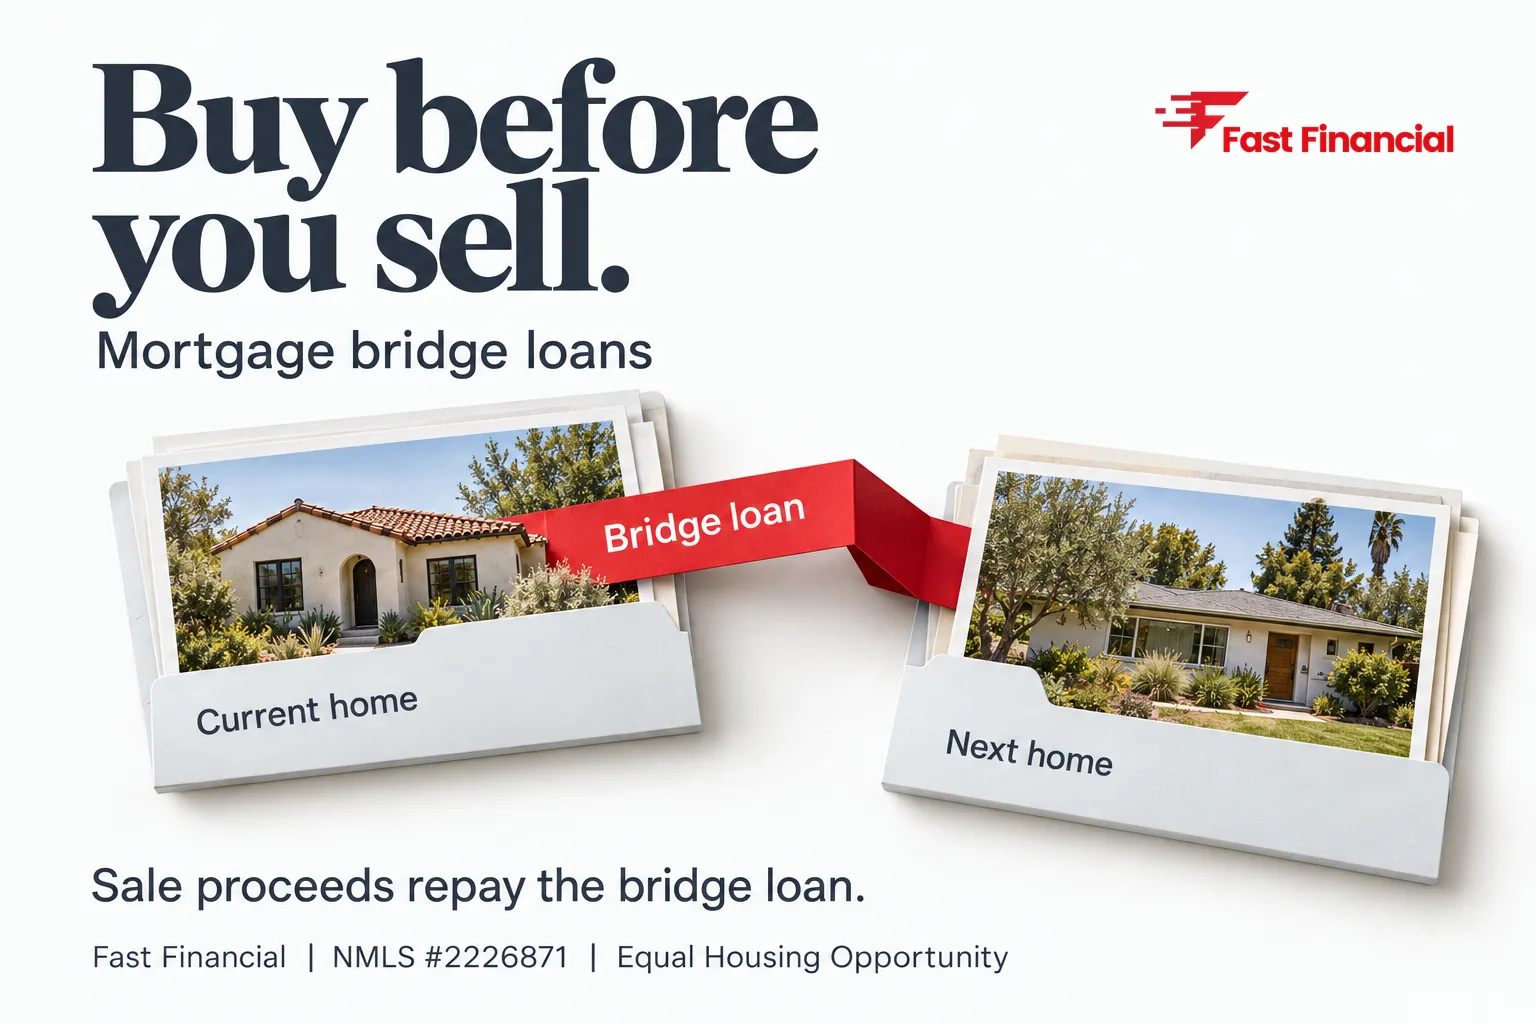
A mortgage bridge loan is short-term financing, secured by real estate, that covers a gap in your timeline. Most often that means funding the purchase of your next home before your current one sells. It is a tool for timing problems, not a long-term mortgage, and it only works when you have a clear plan to pay it off.
This guide covers how bridge loans for mortgage borrowers actually work, what lenders look at, and what to compare before you sign. If you want the basic primer first, start with what a bridge loan is.
How do mortgage bridge loans work?
You borrow against the equity in a property you already own. The proceeds go toward the down payment or purchase of the next property. When the old home sells, the sale proceeds repay the bridge loan.
There are two common structures:
- Standalone bridge loan. A separate short-term loan, often secured by your current home. Your existing mortgage stays in place. The bridge sits behind it or, in some cases, replaces it.
- Combined or "swing" structure. The lender rolls your existing mortgage balance and the new funds into one short-term loan. Fewer moving parts, but your current loan is paid off as part of the deal.
Terms are short by design. Payments are commonly interest-only or deferred until payoff, and the cost usually shows up in lender fees and the interest rate. Both vary by borrower, property, and market, so get a written quote rather than relying on any number you see online.
Who actually uses a bridge loan?
Three borrower types show up most:
- Move-up buyers in a competitive market. A contingent offer (one that depends on selling your home first) can lose to a clean offer. A bridge lets you compete without that contingency.
- Sellers who need cash out of their current home. You find the right house before your listing closes, and your down payment is locked in your old equity.
- Investors. Bridge financing lets you move fast on a property that needs work or a different permanent loan later. See our guide to fix and flip loans for Antelope Valley investors.
In practice, if you can comfortably carry two housing payments for a stretch, a bridge is a convenience. If you can't, it is a risk.
What do lenders look at for a bridge loan?
Bridge lending leans on the property more than a standard purchase loan does, but it is not no-questions lending. Here is what lenders actually look at:
- Equity in the current home. This is the collateral and the repayment source. More equity means more options.
- Realistic exit plan. The lender wants to see how the loan gets repaid: a sale, a refinance, or other funds. A listing agreement, a market analysis, or a signed purchase contract helps.
- Your debt-to-income picture. Some programs count both housing payments when qualifying, which is why understanding debt-to-income ratio for a mortgage matters before you apply.
- Credit and reserves. Strong credit and cash on hand widen your options.
- Property condition and value. An appraisal or valuation drives how much you can borrow.
Programs differ a lot from one lender to the next. That is where a broker earns their keep, because the right structure depends on your specific equity, timeline, and plans.
Does Rocket Mortgage do bridge loans?
This is one of the most-searched questions on the topic, and the honest answer is that big retail lenders change their product menus. Some do not offer bridge loans at all. Others offer them only through certain channels or in certain states. Check with any lender directly before assuming a product exists.
A mortgage broker is not tied to one lender's menu. Fast Financial can compare bridge and alternative structures across multiple sources, which matters when the product you need isn't on a single lender's shelf.
What are the risks of a bridge loan?
Be straight with yourself about these:
- Your old home doesn't sell on schedule. The bridge comes due whether or not your buyer shows up. A price reduction or a longer-than-expected listing can squeeze you.
- Two payments at once. Even if bridge payments are deferred, you may still carry your existing mortgage plus the new one.
- Higher cost than conventional financing. You are paying for speed and flexibility. Weigh that against the value of winning the home.
- Appraisal and contingency surprises. If your new purchase has loan or appraisal conditions, know how they interact with the bridge. Our guide on appraisal and loan contingencies in California covers that.
The number that matters is how long you can hold both properties without stress. Build your plan around the slow case, not the best case.
What are the alternatives to a mortgage bridge loan?
Before you commit, compare these:
| Option | How it works | Best fit |
|---|---|---|
| Bridge loan | Short-term loan secured by current or new property | Buying before selling when speed matters |
| HELOC or home equity loan | Borrow against equity in your current home | Borrowers with time to set it up before listing |
| Cash-out refinance | Replace your mortgage and pull equity out | Borrowers who can wait and want longer-term financing |
| Sale-contingent offer | Make your purchase depend on selling first | Less competitive markets |
| Hard money loan | Asset-based short-term loan with flexible underwriting | Investors, or borrowers who don't fit standard programs |
A HELOC opened before you list can be a cheaper way to fund a down payment. See HELOC vs. second mortgage for how they compare. If your situation doesn't fit conventional guidelines, read about hard money loans in California.
What about commercial mortgage bridge loans?
Commercial bridge loans follow the same logic but apply to income-producing or commercial properties: apartment buildings, retail, mixed-use. They are typically underwritten on the property's value and the borrower's plan for stabilizing it, then refinanced into longer-term debt.
Are they safe? That depends on the deal, not the label. The core risk is the same as any bridge: if the exit (a sale or a refinance) falls through or takes longer, you are left holding short-term debt. Anyone financing a larger property should map out the exit before taking the loan. For longer-term options on multifamily, see apartment loans in California.
How do I get started?
Here's the move. Before you shop for a bridge, answer three questions:
- How much equity do I have, and how do I access it?
- What is my honest timeline to sell?
- What happens if the sale takes longer than planned?
If those answers hold up, talk to a broker who can price out the bridge alongside the alternatives. Get your rate reviewed and see where you stand. You can also call Fast Financial at (661) 512-4141 or stop by the office at 190 Sierra Ct Ste 324, Palmdale, CA 93550. We also work with borrowers across the Los Angeles area. Fast Financial is licensed in California, NMLS #2226871. All loans are subject to underwriting approval, and terms vary by borrower and market.
Frequently asked questions
Are bridge loans only for buying a home before selling the old one?
No. That is the most common use, but bridge financing also helps investors who need to close quickly on a property and refinance into a longer-term loan afterward.
Can I get a bridge loan with no income documentation?
It depends on the program. Some lenders weigh the property and your exit plan more heavily than income, but many still review income, credit, and assets. Ask for the specific documentation requirements up front.
How long does it take to close a bridge loan?
Often faster than a standard mortgage, but timing depends on the lender, the property, and how quickly your documents and valuation come together. Ask for a realistic timeline in writing.
What happens if my home doesn't sell before the bridge loan comes due?
You would need to repay, extend, or refinance the loan, and an extension isn't guaranteed. This is why a conservative sale timeline and a backup plan matter before you borrow.
Is a bridge loan the same as a hard money loan?
They overlap but aren't identical. A bridge loan is defined by its purpose, bridging a gap, while hard money is defined by its asset-based underwriting. Some bridge loans are hard money loans, and some are not.