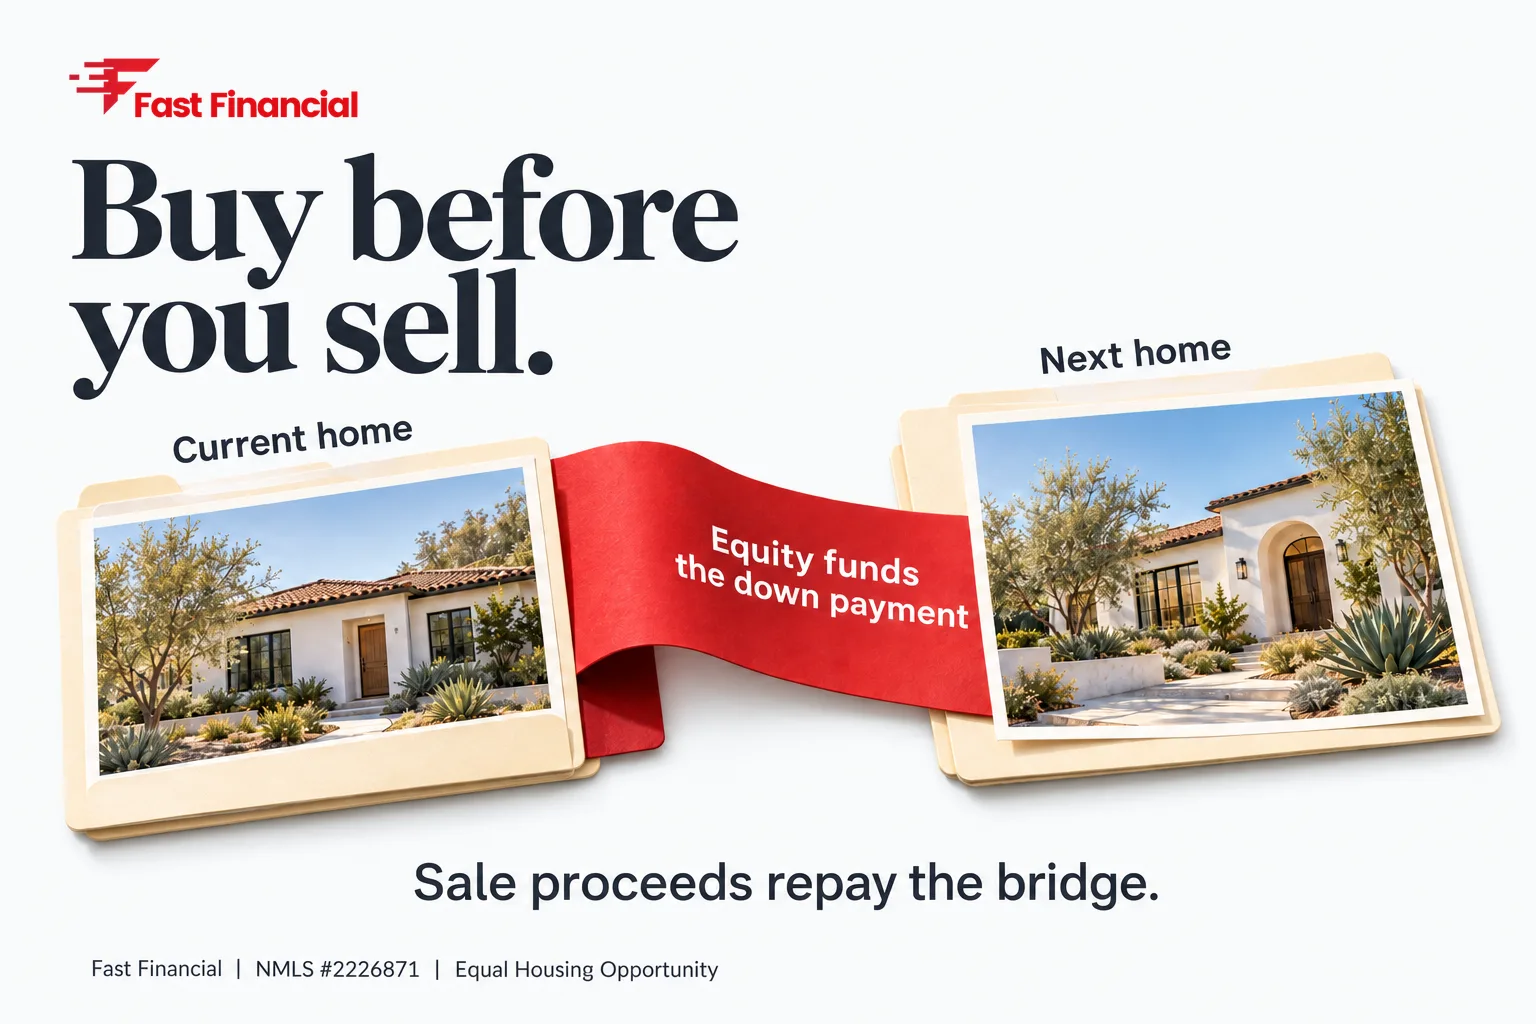
A mortgage bridge loan is short-term financing, secured by your current home, that gives you cash for the down payment on your next one before the first one sells. When the old home closes, the bridge gets paid off from the sale proceeds. It's a timing tool, and it carries a real cost for that convenience.
At Fast Financial, we see this most often in competitive California markets, where a "buy first, sell later" offer can beat one with a home-sale contingency. Here's how to tell whether a bridge fits your situation.
How does a mortgage bridge loan actually work?
You already own a home with equity. A bridge lender uses that equity to fund the down payment and sometimes closing costs on the purchase. In practice, there are two common setups:
- A second lien on your current home. The bridge sits behind your existing mortgage, and you keep that first mortgage in place.
- A bridge that pays off your current mortgage. The new loan replaces it, and it is repaid in full when the home sells.
Many bridge loans are structured so you make no monthly payments during the bridge period. Instead, the interest and fees are paid at payoff. Structures vary by lender, so confirm the details in writing before you commit.
The number that matters is your equity: the home's value minus what you owe. Lenders look at combined loan-to-value (CLTV) on the old home, and they look closely at whether you can carry both homes if the sale drags.
Who is a bridge loan a good fit for?
Bridge loans work best when three things are true:
- You have meaningful equity in the home you're selling.
- You need to move fast, because the purchase is competitive or the timing won't line up.
- You can qualify for the new mortgage, with the bridge debt counted, if your old home hasn't sold yet.
That last point trips people up. When both homes carry debt at the same time, your debt-to-income ratio gets tested. Lenders may count both payments, or the bridge obligation, unless the old home is under contract. Read our guide to debt-to-income ratio for a mortgage before you shop. It will show you what a lender can and can't ignore.
Bridge loan vs. HELOC vs. contingent offer: which is the better move?
A bridge isn't the only way to get the down payment. Compare the options on what they solve:
| Option | How it works | Main tradeoff |
|---|---|---|
| Bridge loan | Short-term loan on your current home's equity | Higher cost for speed |
| HELOC | Revolving credit line on your current home | Usually has to be opened before you list |
| Home-sale contingency | Your offer depends on selling first | Weaker offer in a competitive market |
| Cash-out refinance | New mortgage on current home, taking equity out | Changes your existing loan |
If you have time to plan, a HELOC is often the cheaper tool. Many lenders won't open one on a home that's already listed, so the order matters. Our breakdown of HELOC vs. second mortgage shows how these differ. If you're comfortable replacing your first mortgage, see how a cash-out refinance works.
A contingent offer costs nothing in fees, but sellers often pass on it. For how those clauses work in California, read appraisal and loan contingencies.
What does a bridge loan cost?
Expect it to cost more than a standard mortgage. Bridge pricing typically includes interest plus origination fees, and sometimes appraisal and title charges. Rates and fees vary by borrower, property, and market, so we don't quote numbers here. Any lender that quotes you a figure has to disclose the full cost, so ask for the whole picture, not just the headline.
Compare bridge cost to what the alternative costs you. If a bridge lets you win a home you'd otherwise lose, or avoids carrying a rushed sale at a discount, it can pay for itself. If you have no deadline, it probably doesn't. Use our mortgage calculators to model carrying both homes for a stretch before you decide.
What are the risks of a bridge loan?
Be honest with yourself about three risks:
- The old home doesn't sell on schedule. The bridge comes due regardless.
- The sale price comes in lower than expected, shrinking the equity you counted on.
- You stack two loans and strain your budget until the sale closes.
Build a worst-case plan before you sign. Know how you'd pay it off if the home needed a price cut or a longer listing period. For a broader look at short-term, asset-backed financing, see what a bridge loan is and what a hard money loan is.
Do investors use bridge loans too?
Yes. Investors use bridge financing to close fast on a purchase, then refinance into permanent financing once the property is stabilized or repaired. That's common with fix-and-flip deals in the Antelope Valley. Commercial bridge loans exist too, but they're underwritten differently, usually focused on the property and the exit plan. If you plan to hold the property as a rental, a DSCR loan is often the take-out loan after the bridge.
What should you ask a lender before taking a bridge loan?
- Is the bridge a second lien, or does it replace my current mortgage?
- Are payments deferred, and when do interest and fees come due?
- What happens if my home hasn't sold by the payoff date?
- Is there a prepayment penalty?
- How will the bridge debt affect qualifying for my new mortgage?
A broker can shop several programs at once, which matters because bridge availability and structure differ a lot from lender to lender. Not every lender offers one, so ask each directly instead of assuming.
Get your options reviewed
Fast Financial is a California mortgage broker (NMLS #2226871). We can walk through your equity, your timeline, and whether a bridge, HELOC, or another route fits. See where you stand, call us at (661) 512-4141, or stop by our office at 190 Sierra Ct Ste 324, Palmdale, CA 93550. If you're buying across Los Angeles, our Los Angeles mortgage broker page covers that service area. All loans are subject to credit approval, and terms vary by borrower. Equal Housing Opportunity.
Frequently asked questions
Can I get a mortgage and a bridge loan at the same time?
Often yes, but the new mortgage lender has to count the bridge debt when qualifying you. Plan the sequence with your loan officer before you make an offer.
Does Rocket Mortgage do bridge loans?
Product menus at large retail lenders change, so check with any lender directly rather than relying on a third-party answer. A mortgage broker can compare several lenders' programs side by side.
Is a bridge loan the same as a hard money loan?
They overlap. Both are short-term and asset-backed, but a bridge is usually tied to a pending home sale or purchase, while hard money is more often used by investors. Pricing and underwriting differ by lender.
Are commercial mortgage bridge loans safe?
They carry more risk than a standard mortgage because they depend on an exit plan, such as a sale or refinance, that must work on time. Stress-test that plan before borrowing.
Will a bridge loan hurt my chances of getting approved for the new home loan?
It can, because it adds debt to your profile. If the old home is under contract, the lender may treat it differently, so ask about the specific documentation required.