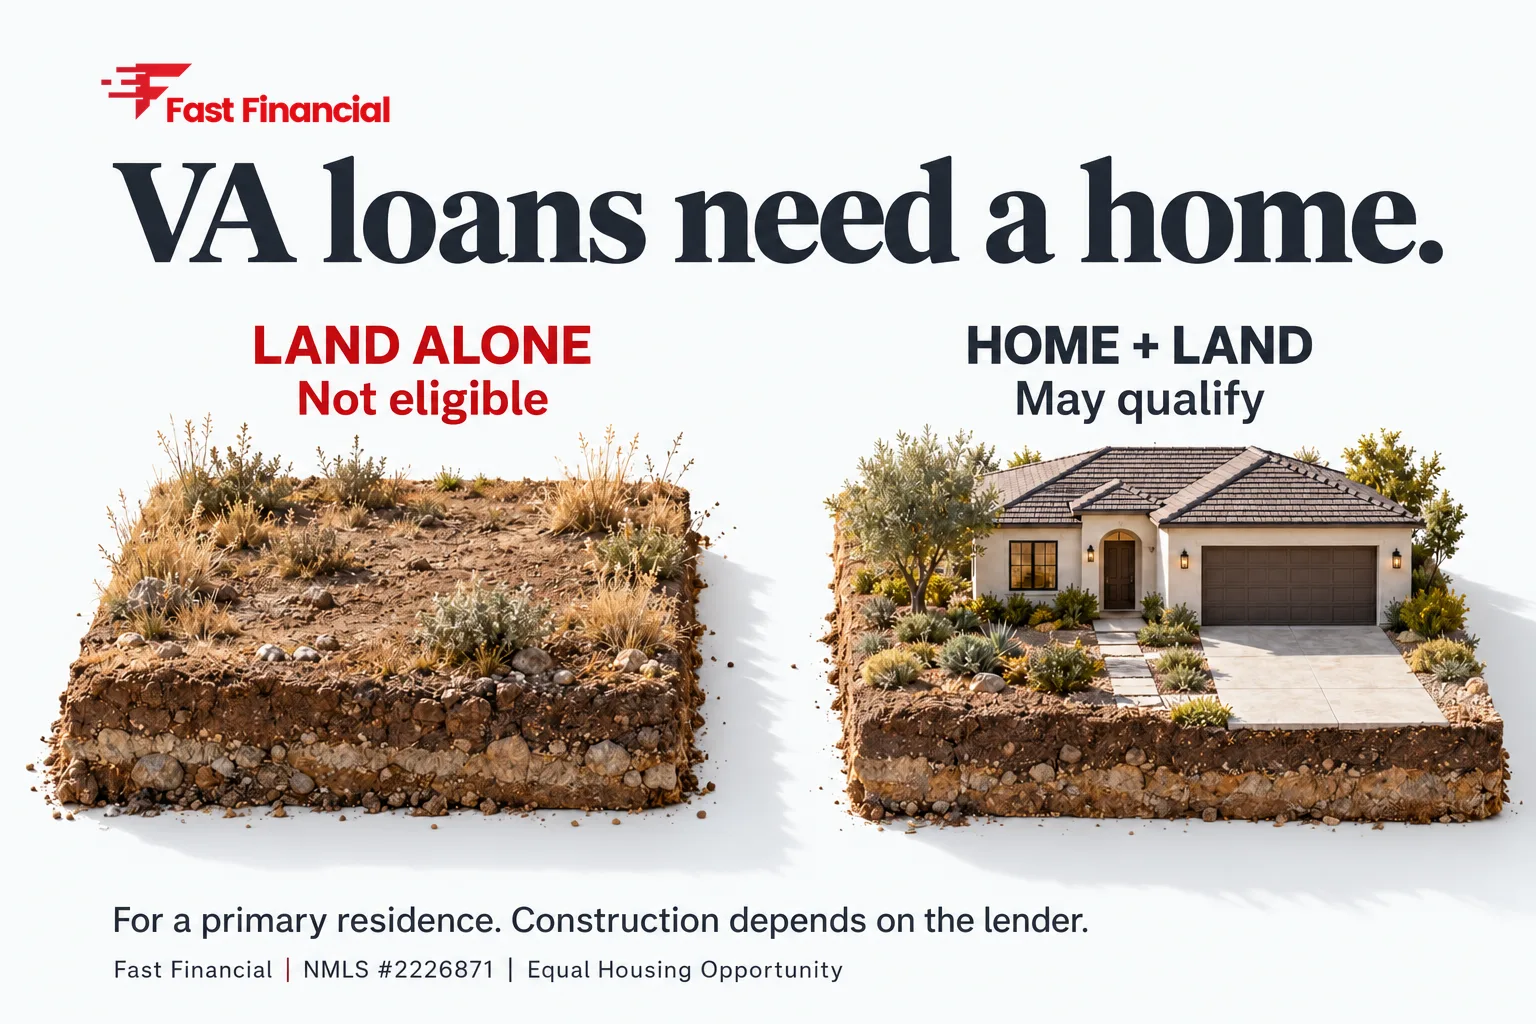
A VA loan generally can't be used to buy vacant land on its own. The VA guaranty is meant to finance a home you'll live in, so a raw lot with no dwelling doesn't qualify. There are still ways to use your benefit on land: buy a home that sits on acreage, finance a lot together with new construction, or refinance into a VA loan after you build.
Here's how each path works and where veterans get stuck.
Can I use a VA loan to buy raw land?
No. The VA doesn't guarantee loans for land alone, whether it's a vacant lot, a desert parcel, or acreage you plan to build on someday. The loan has to be for a primary residence you intend to occupy, and an empty lot isn't one yet.
If a lender tells you they'll do "a VA loan for land," read the fine print. It's usually a different product, like a land loan, a hard money loan, or a construction loan, with different terms and no VA guaranty on the land piece.
What can a VA loan do with land?
The VA is flexible when the land comes with a home. These are the real options:
| Path | VA guaranty applies? | What to know |
|---|---|---|
| Buy an existing home on a large lot | Yes | The property has to be residential in character and pass the VA appraisal. |
| Buy a lot + build (construction-to-permanent) | Yes, with the right lender | Few lenders offer it. Builder approval and draw inspections are part of the deal. |
| Buy the lot with other funds, then build with VA financing | Possibly | The lot is typically owned first; the construction loan then covers the build. |
| Buy land with cash or another loan, build, then refinance to VA | After completion | The VA loan replaces the construction financing once the home is done. |
| Buy a fixer on land and renovate | Yes | See the option. |
How does a VA construction loan work?
The VA doesn't lend money. It guarantees loans made by private lenders, and most lenders skip VA construction loans because of the added risk and paperwork. The ones who offer them typically require:
- A VA-approved builder or one that meets the lender's standards. Your builder needs a solid track record and the right licensing.
- Approved plans and specs. The VA appraisal is based on what the finished home will be worth.
- Staged draws. Money is released as work is inspected, not all at once.
- Your own qualifying. Credit, income, and debt-to-income still apply. The numbers that matter are in our guide to debt-to-income ratio for a mortgage.
Lender overlays are where it gets tricky. The VA sets a baseline, but each lender adds its own credit and documentation rules. If you're curious what credit lenders expect, see the minimum credit score for a VA loan.
What about the land itself on a construction deal?
If you don't own the lot yet, some construction-to-permanent programs let the lot purchase and the build be financed together. If you already own it, the lot's value can often count toward your equity in the project. How the land is treated depends on the lender, the plans, and the appraisal, so get it reviewed before you sign a purchase contract.
Don't assume the lot is financeable. A lot with no road access, utilities, or a clear building path can sink the whole loan. Confirm those things during escrow, and keep your timeline in mind when you read about appraisal and loan contingencies in California.
Can I buy a home on acreage with a VA loan?
Often, yes. A house on a larger parcel can work if the property is primarily residential, the land is typical for the area, and the appraisal supports it. Problems show up when the acreage looks like a business, such as working farmland or a parcel that could be subdivided. That can draw extra scrutiny or disqualify it.
In the Antelope Valley, larger lots are common, which makes this a realistic path for many veterans. If you're stationed or retired near the base, our VA loan guide for Edwards Air Force Base homebuyers covers the local angle.
What are the alternatives if I just want the land?
If your goal is a vacant lot, here's the move:
- Pay cash or use equity. A cash-out refinance on a property you own can fund a land purchase. See how a cash-out refinance works.
- Use a land loan. These are offered by banks and credit unions, usually with stricter terms than a home loan.
- Use a short-term loan. A bridge loan can cover the gap if you're selling another property first.
- Build, then convert. Once the home is finished, a VA purchase or refinance can pay off the construction financing. Read up on VA loan benefits to see what you'd be moving into.
Investors have different tools. If the land will hold a rental, a DSCR loan may fit better than a VA loan, since VA financing requires you to occupy the home.
Does using land affect my VA entitlement?
It can. Your entitlement is the amount of the guaranty available to you, and you may have a portion tied up if you have an existing VA loan. If you buy a lot and later want VA financing for the build, make sure your remaining entitlement and the funding fee rules fit the project. A lender who works with VA files daily can tell you where you stand before you commit to a parcel.
What should I do first?
Start with a conversation, not a contract. Before you make an offer on a lot or a builder deposit:
- Get a VA pre-approval so you know your qualifying picture. Here's what to expect in VA loan pre-approval.
- Ask whether the lender actually offers VA construction financing.
- Confirm utilities, access, and zoning on the parcel.
- Run your own payment scenarios with our mortgage calculators.
At Fast Financial, we're a licensed California mortgage broker (NMLS #2226871) and we shop lenders on your behalf, which matters most on niche deals like construction and land. Rates and terms vary by borrower and market, and approval depends on your full file.
Ready to see where you stand? Get your rate reviewed, call us at (661) 512-4141, or stop by the office at 190 Sierra Ct Ste 324, Palmdale, CA 93550. If you're in the Antelope Valley, we're local to you.
Frequently asked questions
Can I use a VA loan to buy a vacant lot?
Generally no. The VA guaranty is for financing a primary residence, so a vacant lot on its own doesn't qualify. You'd need to pair the lot with construction or look at other financing.
Does the VA offer construction loans?
The VA guarantees loans but doesn't lend directly, and only some private lenders offer VA construction financing. If you want this route, ask early whether your lender does it.
Can I buy a house on several acres with a VA loan?
Often, if the property is residential in character, the acreage is typical for the area, and the appraisal supports it. Properties that look like working farms or income-producing land can run into problems.
Can I refinance into a VA loan after building a home?
Yes, in many cases. You can use other financing for the lot and the build, then refinance into a VA loan once the home is complete. Check your options with a lender on refinance options before you start.
Do I have to live in the home?
Yes. VA loans are for a primary residence, and you're expected to occupy the home within a reasonable time after closing.