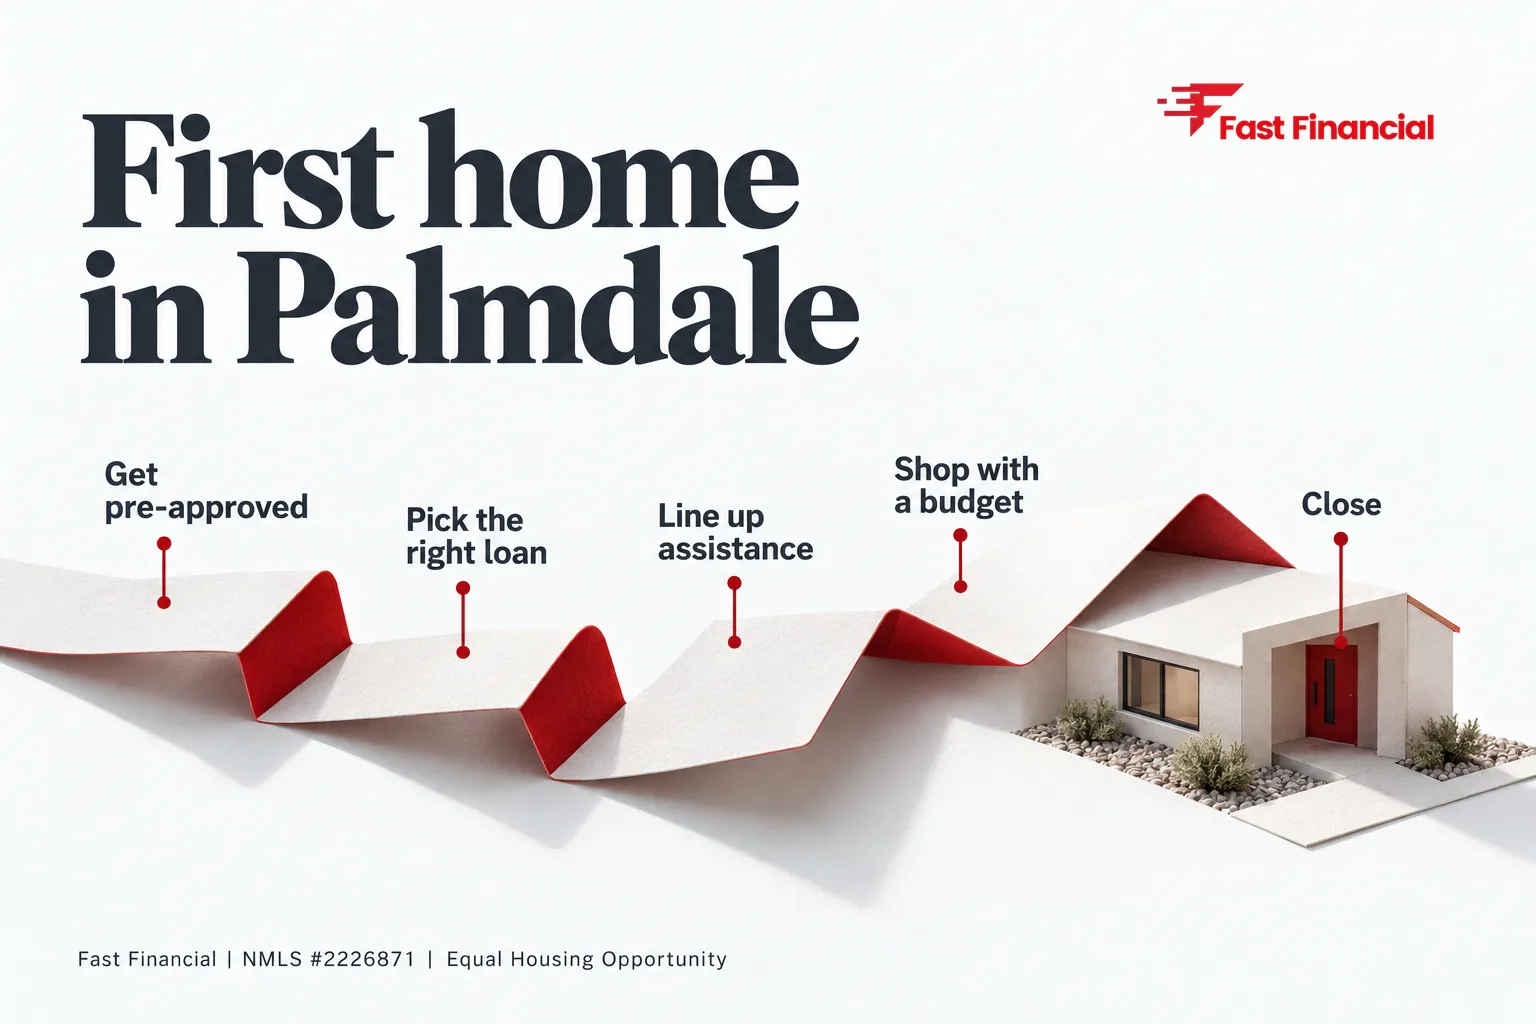
A first time home buyer in Palmdale gets to the closing table by doing five things in order: get pre-approved, choose the right loan program, line up any down payment help, shop to a budget you've actually stress-tested, and manage the escrow period. Do them in that order and the process is far less mysterious than it looks.
Palmdale and the wider Antelope Valley are a common starting point for California first-timers. Here's the move at each stage, and what lenders actually look at.
Where do I start as a first time home buyer in Palmdale?
Start with your numbers, not with listings. Before you tour a single house, find out what a lender would approve you for and what you're comfortable paying. The two are often different.
Pull your credit reports, list your monthly debts, and gather the basics: recent pay stubs, W-2s or tax returns, and bank statements. Then run your own math with the mortgage calculators so you know your comfort zone before a lender tells you their ceiling.
For the income side of that question, see how much house you can afford in Palmdale and how much income you need to buy a house in California.
What does a mortgage pre-approval actually do?
A pre-approval tells sellers and agents you're a real buyer. A lender reviews your credit, income, assets, and debts, then issues a letter stating what you're likely able to borrow, subject to a property appraisal and final underwriting.
In a competitive offer, that letter matters. It is not a final commitment to lend, and it isn't a guarantee of approval. For the full process, read mortgage pre-approval in California.
The number that matters most here is your debt-to-income ratio. Lenders compare your monthly debt payments to your gross monthly income. Here's how to calculate DTI and what lenders allow.
Which loan programs fit a first-time buyer?
Most first-time buyers in the Antelope Valley land in one of a few buckets. Which one fits depends on your credit, savings, income type, and whether you've served in the military.
| Program | Often a fit when… | What to know |
|---|---|---|
| FHA | Credit is still being built or savings are limited | Flexible qualifying, but mortgage insurance applies |
| Conventional | Credit is solid and you want lower long-term cost | Pricing is tied closely to credit and down payment |
| VA | You're a veteran or active-duty service member | No monthly mortgage insurance; entitlement rules apply |
| Bank statement / non-QM | You're self-employed and tax returns understate income | Alternative documentation; terms vary by lender |
Rates and terms vary by borrower and market, so any quote needs to come from a lender reviewing your actual file.
If FHA looks like your lane, FHA loans in Palmdale covers how it works locally, and conventional vs. FHA helps you compare. Veterans, including those tied to Edwards Air Force Base, should read the VA loan guide for Edwards AFB homebuyers.
Is there down payment help for first-time buyers in the Antelope Valley?
Yes, programs exist, but eligibility, funding, and terms change. Assistance generally comes from state agencies such as CalHFA, from local and county programs, or from gift funds from family. Each has its own income limits, buyer education requirements, and rules about how it layers with your primary loan.
Check current program details directly with the administering agency before you count on any of it. Our overview of first-time homebuyer programs in the Antelope Valley is a good starting map.
If a relative is helping with funds, lenders will want documentation. Here's the gift letter template and what lenders require. And if you're wondering about buying with little saved, see no-money-down home loans in California.
What does it really cost to buy, beyond the price?
The sticker price is only part of it. Plan for these categories:
- Down payment, based on the program you choose
- Closing costs, including lender, title, escrow, and prepaid items
- Reserves, meaning money left in the bank after closing
- Ongoing costs: property taxes, homeowners insurance, mortgage insurance if it applies, and any HOA dues
Your property tax and insurance are often collected monthly into an escrow (impound) account, which changes how your payment is built. How escrow accounts work in California breaks it down. For closing costs, see what California closing costs include.
One Antelope Valley note: some newer tracts carry special assessments such as Mello-Roos on top of regular property taxes. Ask your agent early and check the preliminary title report, because those charges affect what you can afford each month.
What happens between accepted offer and keys?
Once your offer is accepted, the clock starts. You'll typically order the appraisal and inspections, review the title report, lock your rate if you choose to, and respond quickly to underwriter requests.
Your contingencies protect you during this window. Appraisal and loan contingencies in California explains what they cover and when they expire. If you want to understand who's reviewing your file, read what a mortgage underwriter does.
Two habits keep files moving. Respond to document requests the same day, and don't change your financial picture. Skip new credit cards, car loans, large unexplained deposits, and job changes without talking to your loan officer first.
Terms you'll hear along the way are covered in mortgage terms every California first-time buyer should know. For a full to-do list, use the first-time homebuyer checklist.
What if my income or credit isn't textbook?
Plenty of Palmdale buyers are self-employed, contract workers, or rebuilding after a rough stretch. That doesn't automatically rule out buying. It means the loan program and documentation need to match your situation.
Self-employed buyers should read how to get a mortgage when you're self-employed in California. If your credit needs work first, how to raise your credit score lays out what actually moves it.
Ready to see where you stand?
Fast Financial is a California-licensed mortgage broker (NMLS #2226871). A broker can compare options across multiple lenders instead of fitting you into one product. Get your rate reviewed to see where you stand, or call us at (661) 512-4141.
Our office is local to Palmdale buyers: 190 Sierra Ct Ste 324, Palmdale, CA 93550. Call or stop in, and we'll walk through your numbers. You can also learn more about Fast Financial.
Equal Housing Opportunity. This article is general information, not a loan offer or commitment to lend. Programs, rates, and terms vary by borrower and market.
Frequently asked questions
Do I need perfect credit to buy my first home in Palmdale?
No. Several loan programs are built for borrowers with imperfect credit, though your score affects pricing and which programs you can use. Reviewing your reports early gives you time to fix errors and improve your profile.
How long does it take to buy a house in Palmdale?
It varies. Preparation before you shop can take weeks to months, and once you're under contract the loan process depends on the appraisal, your documentation, and how quickly each party responds. Timelines are never guaranteed.
Can I use gift money for my down payment?
Often yes, depending on the loan program. Lenders typically require a signed gift letter and a paper trail showing where the funds came from.
Is it better to rent in the Antelope Valley or buy?
It depends on how long you'll stay, your savings, and your monthly budget. Comparing your likely all-in monthly cost of owning against your rent, with real numbers from a lender, is the clearest way to decide.
Do I need a real estate agent and a mortgage broker?
They do different jobs. Your agent finds and negotiates the property, and your mortgage broker structures and shops the financing. Working with both early keeps your offers strong and your budget realistic.