Yes, you can get a mortgage loan after foreclosure. You have to clear the waiting period for the loan program you want, and then show a lender that your credit, income, and savings are solid again. The wait depends on the loan type, and some options open up sooner than most borrowers expect.
Here's how to think about it: a foreclosure is a timing problem first and a credit problem second. Get the timing right and the rest becomes a checklist.
How long do you have to wait for a mortgage after foreclosure?
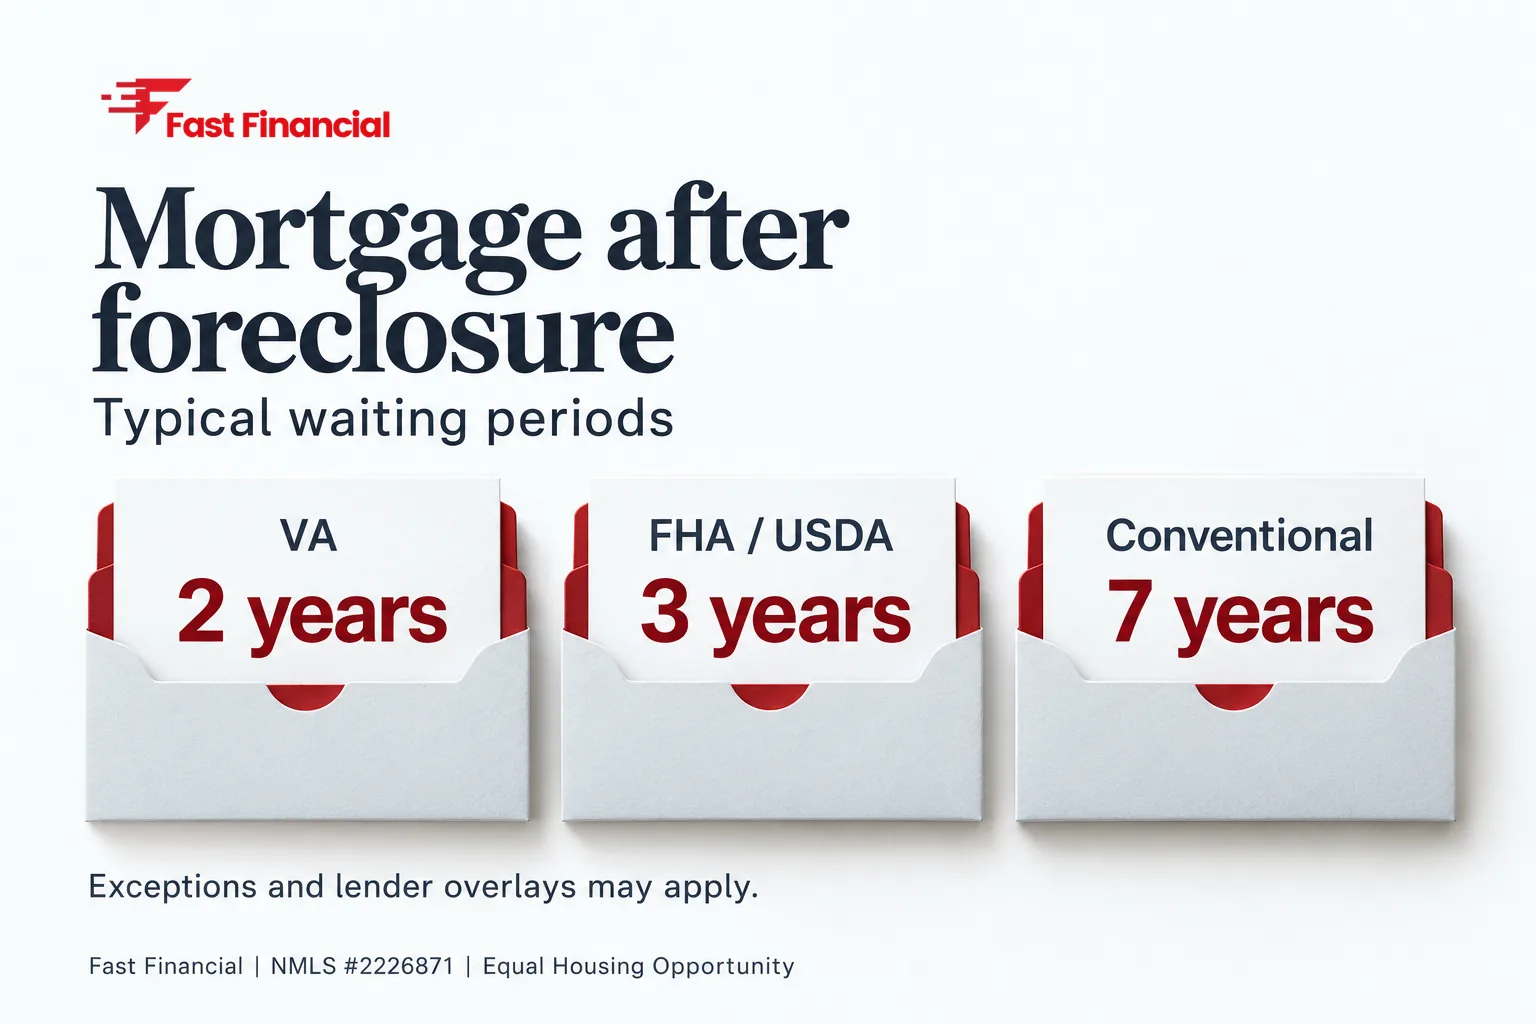
Each loan program sets its own clock, usually counted from the date the foreclosure was completed, not the date you missed your first payment. These are the standard guidelines from the agencies behind each program:
| Loan type | Typical waiting period | Notes |
|---|---|---|
| Conventional (Fannie Mae / Freddie Mac) | 7 years | Shorter with documented extenuating circumstances, with tighter terms |
| FHA (HUD) | 3 years | Exceptions exist for circumstances outside your control |
| VA | 2 years | Lender overlays can be stricter |
| USDA | 3 years | Same extenuating-circumstance logic applies |
| Non-QM | Varies by lender | Often shorter than agency programs |
Guidelines change, and individual lenders can add their own overlays. Treat the table as a starting map, then confirm the current rules before you plan around a date.
What counts as an "extenuating circumstance"?
It's a one-time event beyond your control that caused the loss of income or a spike in expenses. Think job loss, serious illness, or the death of a wage earner. Poor planning or walking away from a home you could afford doesn't qualify.
Documentation is what decides it. Lenders want a clear timeline: what happened, how your income changed, and proof you recovered. Termination letters, medical records, and bank statements carry more weight than a written explanation alone.
Which loan is the best fit after a foreclosure?
It comes down to your waiting period, your credit, and what you're buying.
- FHA is usually the first door. It has the shortest agency waiting period for most borrowers and flexible credit rules. Read the full FHA mortgage requirements and the FHA credit score requirements before you apply.
- VA is the strongest if you're eligible. Veterans and service members often get a faster timeline. The minimum credit score for a VA loan depends on the lender, so compare more than one.
- Conventional is the long game. The wait is longest, but the loan can make sense for borrowers with strong credit and savings once the clock runs out.
- Non-QM is the speed option. If the agency wait hasn't ended, a non-QM loan may be possible sooner. The trade-off is that terms are set by the individual lender and can be less favorable than agency loans.
What do lenders actually look at after a foreclosure?
The foreclosure is one line in the file. Underwriters weigh the whole picture, and these are the items that matter most:
- Credit since the foreclosure. Clean, on-time payments on every account since the event are the strongest evidence you've recovered.
- Debt-to-income ratio. Lenders want to see that the new payment fits comfortably. Learn how it's calculated in our guide to debt-to-income ratio for a mortgage.
- Stable income. Two years of consistent work history is the baseline. Self-employed borrowers can read how lenders count self-employed income in California.
- Reserves. Savings left after closing show a lender you can absorb a bad month.
- The story. What caused the foreclosure, and what's different now?
Past mortgage lates and other derogatory items in the same period can hurt as much as the foreclosure itself. If your credit has other problems, fix those at the same time.
How does a foreclosure affect my credit report?
Under the Fair Credit Reporting Act, a foreclosure can stay on your credit report for seven years from the date of first delinquency. The damage to your score fades well before it drops off, especially if you build a clean record afterward.
Lenders care less about the age of the foreclosure than about what you've done since. A borrower who has paid every bill on time for several years usually looks stronger than one who is simply waiting out the clock. Our guide on how to raise your credit score covers the moves that carry the most weight.
Can a cosigner help me get a mortgage after foreclosure?
Sometimes, but not the way most people hope. A cosigner or non-occupant co-borrower can strengthen income and debt-to-income numbers, and FHA allows non-occupant co-borrowers under its rules. In most cases, though, the waiting period still applies to you as a borrower on the loan, so a cosigner with clean credit doesn't erase it.
A cosigner also takes on full legal responsibility for the debt. That's a serious ask of a family member, so have the conversation before you put anyone on the application.
What should I do while I wait?
Use the time. Borrowers who prepare during the waiting period tend to apply from a much stronger position.
- Pull your credit reports and dispute errors, including a foreclosure listed with the wrong date.
- Keep every account current, and keep revolving balances low.
- Build a savings cushion beyond the cash you'll need to close.
- Avoid new debt, including car loans and store cards, in the months before you apply.
- Get pre-approved once you're near the end of the wait, so you know where you stand before you shop.
If you still own other property, a refinance may be worth a look, but a recent foreclosure will affect those options too.
Where does Fast Financial fit in?
Fast Financial is a California mortgage broker (NMLS #2226871), which means we can shop programs across multiple lenders instead of fitting you into one product. For a borrower coming off a foreclosure, that matters, because overlays vary widely from lender to lender. A Los Angeles mortgage broker can tell you which programs your timeline fits and which ones to skip.
Approval depends on your full file, and rates and terms vary by borrower and market. We won't promise an outcome. We will tell you plainly where you stand and what would move the needle.
Frequently asked questions
Can I get a mortgage right after a foreclosure?
Rarely through the standard agency programs, because they require a waiting period first. Some non-QM lenders may consider borrowers sooner, with different terms.
Is FHA the easiest loan after a foreclosure?
For many borrowers, yes, because its agency waiting period is shorter than conventional. VA can be shorter still if you're eligible.
Does a foreclosure ruin my credit forever?
No. It can stay on your report for seven years, but its impact fades as you build a record of on-time payments.
Do I need a bigger down payment after a foreclosure?
It depends on the program and the lender. Some programs and extenuating-circumstance exceptions come with tighter terms, so ask your loan professional before you plan your savings.
Ready to see where you stand?
Call Fast Financial at (661) 512-4141 or stop by the office at 190 Sierra Ct Ste 324, Palmdale, CA 93550. You can also get your rate reviewed online. We'll look at your timeline, your credit, and your goals, and map out the next steps.
Fast Financial, NMLS #2226871. Equal Housing Opportunity. This article is general information, not a loan commitment or financial advice. Programs, guidelines, and eligibility change and vary by lender.