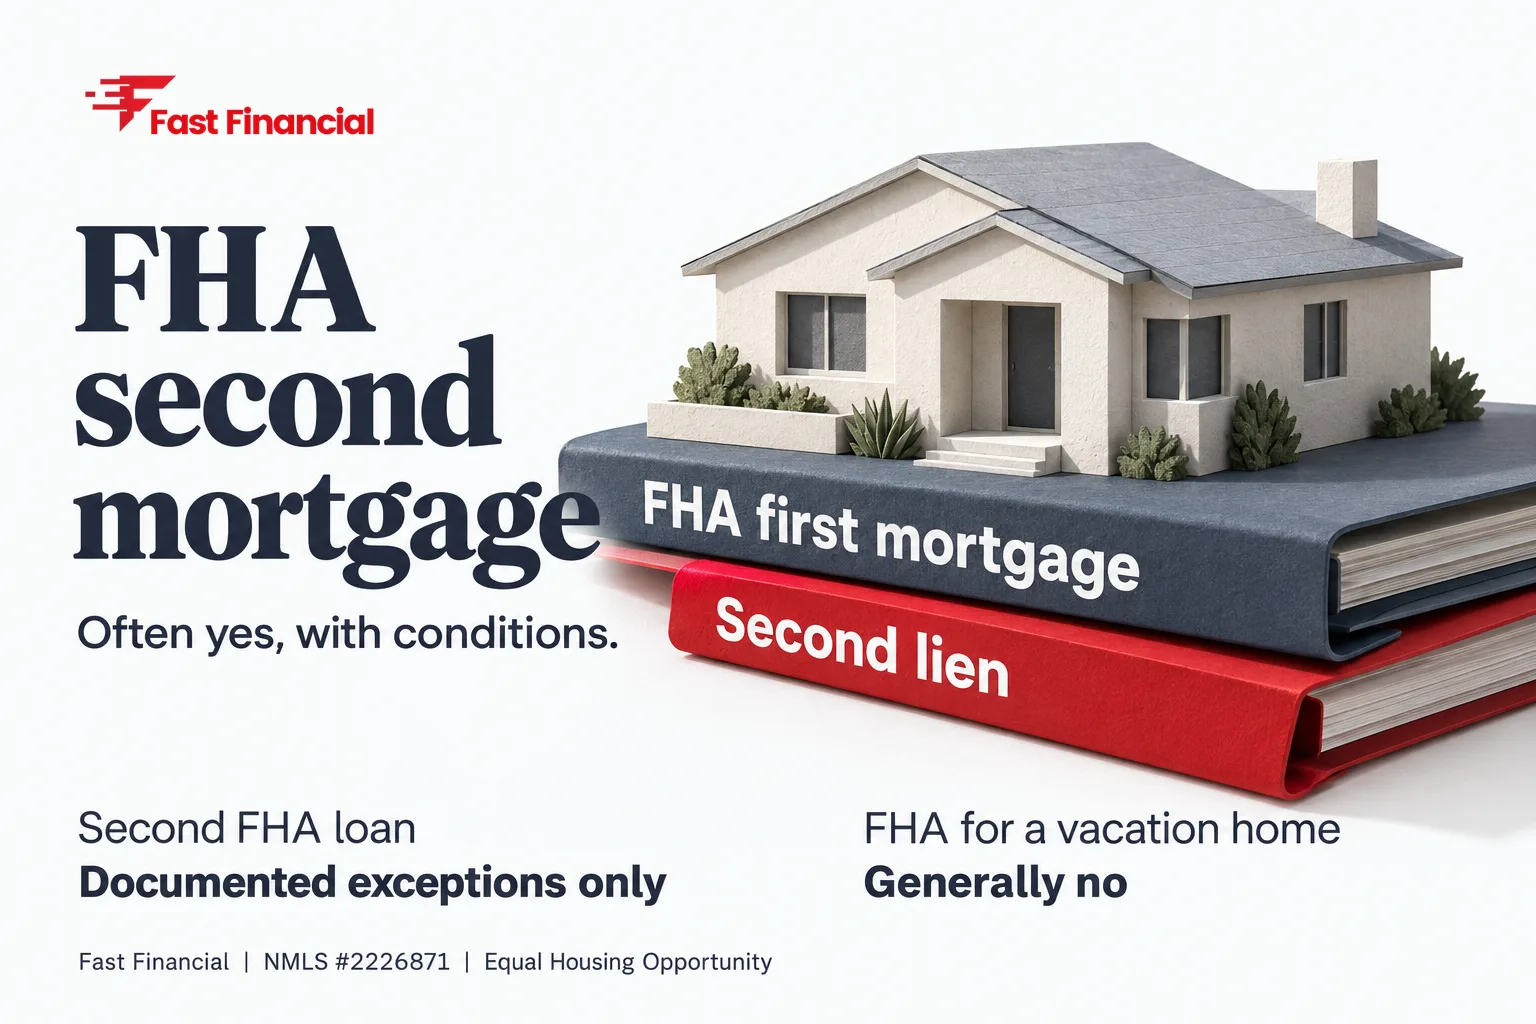
Yes, you can have a second mortgage alongside an FHA loan, but only under FHA's rules for subordinate financing. A second FHA loan, or an FHA loan on a vacation home, is a different question and the answer is usually no. "FHA second mortgage" gets used for three different things, so here's how each one works.
What does "FHA second mortgage" actually mean?
Borrowers usually mean one of three things:
- A second lien behind an FHA first mortgage. This is a home equity loan, HELOC, or down payment assistance loan sitting behind the FHA loan.
- A second FHA loan. This is a new FHA mortgage while you already have one.
- An FHA loan on a second home. This is financing a vacation property with FHA.
Each has different rules. The first is the most workable. The other two are limited by FHA's primary-residence requirement.
Can you put a second mortgage on top of an FHA loan?
Yes, in many cases. FHA calls this subordinate financing. The FHA first mortgage stays in first position, and the second loan sits behind it.
Here's what lenders look at:
- The second lien's terms. FHA has guidelines on how subordinate financing can be structured, including repayment terms and restrictions on certain features.
- Combined loan-to-value (CLTV). The first and second loan together can't exceed what FHA allows against the home's value.
- Your qualifying ratios. The second loan's payment counts in your debt-to-income calculation. See how debt-to-income works for a mortgage for what lenders allow.
- Your credit. The same FHA credit score requirements apply to the overall file.
If you already have an FHA loan and want to tap equity, the first question is whether a second lien makes sense or whether a refinance is the better move. Our breakdown of HELOC vs. second mortgage and second mortgage vs. home equity loan covers the structure differences. Whether the first mortgage's terms are worth protecting is a call to make with the numbers in front of you, and you can use our mortgage calculators to start.
What is a silent second mortgage with FHA?
A silent second is a down payment assistance loan that sits behind your FHA first mortgage. "Silent" means it typically carries no required monthly payment. It's repaid when you sell, refinance, or pay off the first loan, depending on the program.
This is the version most first-time buyers care about. FHA allows these when the assistance comes from approved sources such as government agencies and certain nonprofits. In California, state and local programs can pair with an FHA first mortgage. Program terms, funding, and eligibility change, so confirm details with a participating lender. Our guide to finding a CalHFA lender in Palmdale and the overview of first-time homebuyer programs in the Antelope Valley explain what to expect.
The trade-off is that assistance programs come with their own income limits, occupancy rules, and repayment terms. Read the second lien's note, not just the marketing page.
Can you get a second FHA loan while you have one?
Usually not. FHA generally limits borrowers to one FHA-insured mortgage at a time because the loan is meant for a primary residence.
FHA does recognize exceptions, which a lender must document. Common ones include:
- A job relocation to a different area.
- A growing household that has outgrown the current home.
- A change in family situation, such as a divorce or a co-borrower leaving.
If one applies, expect the lender to ask for supporting paperwork. In many of these cases the first home is sold or converted to a rental, and that changes how the file is built. If you're weighing a rental on the old property, see rental property loans in California.
Can you use FHA for a second home or vacation property?
Generally no. FHA loans are for the home you'll live in as your main residence. Lenders verify that you intend to occupy it, and occupancy is part of the loan agreement. You can't use FHA to finance a vacation home or a pure rental.
If you want a second home, you'd look at conventional financing instead. Our guides to second home mortgage requirements, primary vs. second home mortgages, and closing costs on a second home vs. primary walk through the differences. For investment property, DSCR loans qualify on the property's rental income rather than your personal income.
FHA second mortgage options compared
| Situation | Is it possible? | What to know |
|---|---|---|
| Second lien behind an FHA first (HELOC or home equity loan) | Often yes | Must meet FHA subordinate financing rules and CLTV limits |
| Silent second for down payment | Yes, through approved programs | Program rules, income limits, and repayment terms vary |
| Second FHA loan while holding one | Rarely | Only documented exceptions, such as relocation |
| FHA loan on a vacation home | No | FHA requires primary-residence occupancy |
What's the smart move if you're an FHA borrower?
Start with your goal. If you need cash from equity, compare a second lien against a cash-out refinance and look at what each does to your total cost. If you're buying and short on cash, look at assistance programs before you assume the full burden falls on you. If you want a second property, plan for conventional or investor financing from the start.
Approval depends on credit, income, assets, property, and program guidelines, and nothing here is a promise of any outcome. The FHA mortgage requirements are the baseline your file gets measured against.
Fast Financial can walk through your scenario and show how the pieces fit. To see where you stand, get your rate reviewed, call (661) 512-4141, or stop by our office at 190 Sierra Ct Ste 324, Palmdale, CA 93550. If you're in Palmdale, Lancaster, or anywhere in the Antelope Valley, we're local to you. Fast Financial, NMLS #2226871. Equal Housing Opportunity.
Frequently asked questions
Can I get a second mortgage on an FHA loan?
Often yes, as long as the second lien meets FHA's subordinate financing guidelines and the combined loan-to-value and your debt-to-income stay within limits. Lender overlays can add further requirements.
Can I have two FHA loans at the same time?
Generally no. FHA expects one insured loan on your primary residence, with documented exceptions such as relocation or a growing household.
Can I use an FHA loan to buy a second home?
No. FHA financing requires you to occupy the home as your primary residence, so vacation homes and pure rentals need other loan types.
What is a silent second mortgage on an FHA loan?
It's a down payment assistance loan placed behind your FHA first mortgage, typically with no required monthly payment. It comes due under the program's terms, such as when you sell or refinance.
Can down payment assistance be paired with an FHA loan?
Yes, when the assistance comes from approved sources and meets FHA guidelines. Availability and eligibility vary by program, so confirm with a lender who works with them.